By Editorial Team Get Medical plan on November 14, 2026
Recovering from an injury, surgery, or serious illness is not always as simple as resting for a few days and returning to your regular routine. Sometimes, getting back to everyday activities takes weeks or months of guided treatment. You may need help rebuilding strength, improving movement, managing pain, or learning how to perform certain tasks safely again.
This is where physical therapy and rehabilitation services can make a meaningful difference. However, treatment can involve several appointments, specialist evaluations, exercises, and ongoing progress assessments. Naturally, one of the first questions people ask is whether their health plan will help cover these services.
The short answer is that many health plans do provide benefits for physical therapy and rehabilitation. However, the amount of coverage, eligible treatments, provider requirements, and out-of-pocket costs can vary considerably. Understanding these details before starting treatment can help you avoid unexpected expenses and make more informed decisions about your healthcare.
Let's look at how physical therapy coverage works, which services may qualify, and what you should check before scheduling your first appointment.
What Are Physical Therapy and Rehabilitation Services?
Physical therapy is a healthcare service focused on improving movement, strength, flexibility, balance, and physical function. It is commonly recommended when an injury, illness, surgery, or health condition affects a person's ability to move comfortably or perform everyday activities.
For example, someone recovering from knee surgery may need physical therapy to regain joint movement and rebuild muscle strength. A person who has experienced a stroke may need rehabilitation to improve balance, coordination, and mobility.
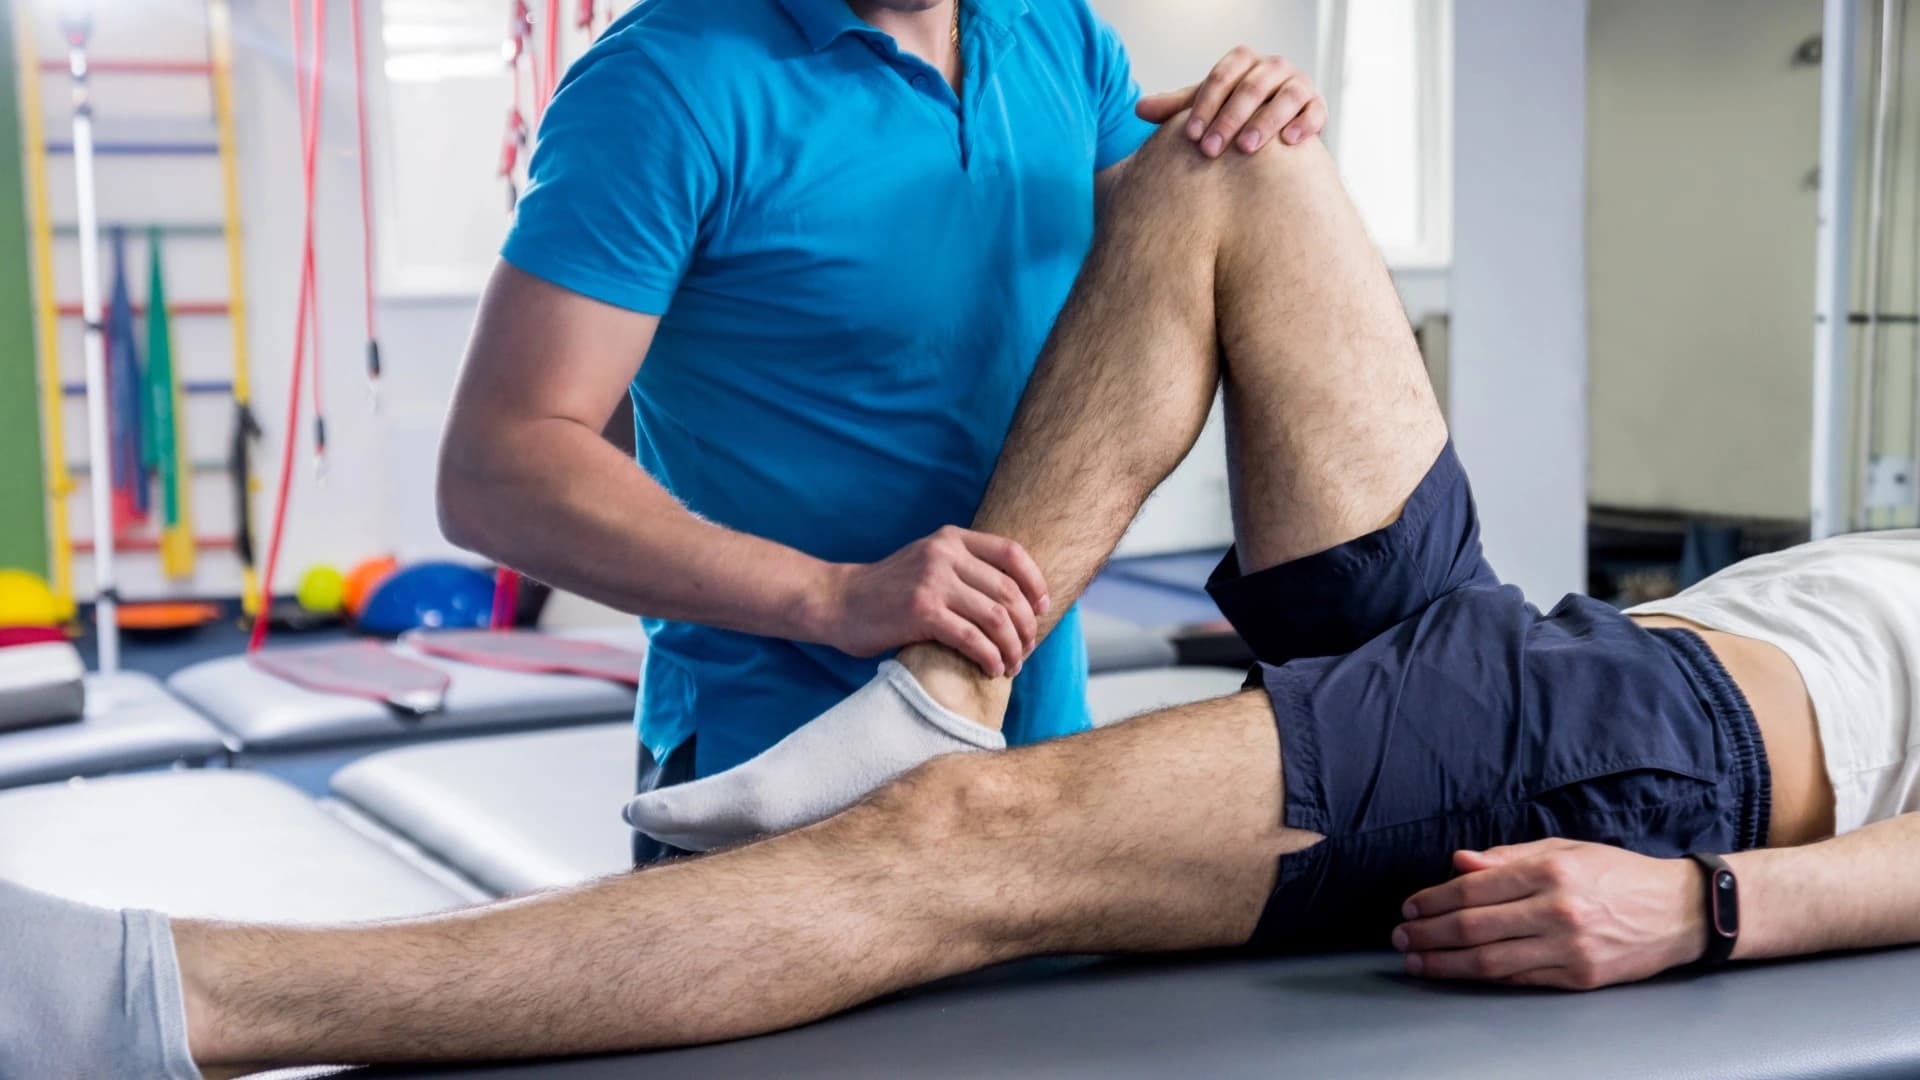
A licensed physical therapist evaluates the patient's condition and develops a treatment plan based on their needs and recovery goals. Treatment may involve guided exercises, stretching, mobility training, balance exercises, movement techniques, and other therapeutic methods.
Rehabilitation is a broader term. It can include physical therapy, occupational therapy, speech-language therapy, and other services designed to help someone recover or improve abilities affected by an illness, injury, or disability.
These services can take place in different settings, including outpatient clinics, hospitals, rehabilitation facilities, skilled nursing facilities, and, when appropriate, at home.
Do Health Plans Cover Physical Therapy?
In many cases, yes. Physical therapy and rehabilitation services may be included in a health plan's benefits when they meet the plan's coverage requirements.
For people enrolled in qualifying Affordable Care Act Marketplace plans, rehabilitative and habilitative services are among the ten categories of Essential Health Benefits. These categories include services that help people recover or improve physical and functional abilities.
However, this does not mean every treatment, appointment, or rehabilitation program is automatically covered. Specific covered services can depend on state requirements and the details of the individual plan. Employer-sponsored plans and other coverage arrangements may have their own benefit structures and requirements. Some plans may cover a broad range of outpatient therapy services, while others may apply specific visit limits, authorization requirements, or provider-network restrictions.
The important thing to remember is that a general benefit category does not tell you everything about your actual coverage. Before beginning treatment, review the plan documents or contact the plan administrator to confirm whether the recommended service is included.
You can also explore different health plan options to understand the types of coverage available and the details worth comparing.
What Is the Difference Between Rehabilitative and Habilitative Services?
These two terms often appear together in health plan documents, but they describe slightly different purposes.
Rehabilitative services help a person regain or improve abilities that were previously developed but lost or impaired because of an injury, illness, or medical condition.
For example, an adult who breaks their leg may need physical therapy to regain the ability to walk comfortably. Someone recovering from a serious illness may need rehabilitation to rebuild strength and improve mobility.
Habilitative services, on the other hand, help someone develop, learn, or improve skills that they may not have fully developed.
For instance, a child experiencing developmental delays may need physical therapy to develop age-appropriate movement skills. A person with a disability may also need ongoing support to develop or improve functional abilities.
Both types of services can involve physical therapy, occupational therapy, or speech-language therapy. The distinction matters because health plan documents may list rehabilitative and habilitative benefits separately. A plan may also have different coverage rules for each category.
When reviewing your benefits, check both sections rather than assuming that coverage for rehabilitation automatically explains what is available for habilitative care.
Which Conditions May Require Physical Therapy?
Physical therapy is recommended for a variety of conditions. Whether a particular treatment qualifies for coverage depends on the plan's rules, the clinical circumstances, and whether the service meets applicable medical necessity requirements.
Some common situations in which physical therapy may be recommended include:
Recovery after surgery: Procedures involving the knee, hip, shoulder, spine, or other parts of the body may require rehabilitation to restore movement and strength.
Sports-related injuries: Sprains, muscle injuries, ligament damage, and other sports-related conditions may benefit from structured physical therapy.
Back and neck problems: Certain spinal conditions, muscle problems, and movement limitations may be treated through guided exercises and therapeutic techniques.
Stroke recovery: Rehabilitation may help individuals improve balance, coordination, movement, and their ability to perform everyday activities.
Joint conditions: People experiencing stiffness, reduced mobility, or functional limitations due to joint conditions may be referred for physical therapy.
Neurological conditions: Some neurological conditions affect muscle control, balance, coordination, and mobility. Physical therapy may form part of a broader treatment approach.
Recovery after serious illness: Extended illness or hospitalization can sometimes lead to reduced strength and physical endurance. Rehabilitation may help patients work toward regaining their previous level of function.
A diagnosis alone does not guarantee coverage. The recommended treatment must still meet the applicable plan requirements.
What Types of Rehabilitation Services May Be Covered?
Coverage can extend beyond traditional physical therapy. Depending on the plan, rehabilitation benefits may include several types of treatment.
1. Outpatient Physical Therapy
Outpatient physical therapy generally involves visiting a clinic, hospital department, or therapy center for scheduled treatment without being admitted as an inpatient. Appointments may include physical assessments, supervised exercises, balance training, and mobility exercises.
This is one of the most common forms of rehabilitation following injuries and surgeries.
2. Inpatient Rehabilitation
Some individuals need a more intensive rehabilitation program after a serious illness, injury, or surgery. Inpatient rehabilitation takes place in a specialized facility or hospital unit. Patients receive coordinated care and therapy while staying at the facility.
The level of care and eligibility requirements differ from those for outpatient treatment. Your plan documents should explain how inpatient rehabilitation is handled.
3. Occupational Therapy
Occupational therapy focuses on helping people perform everyday activities more independently. This may include tasks such as dressing, bathing, preparing meals, using household equipment, or returning to certain work-related activities.
Occupational therapy may be particularly helpful after a stroke, serious injury, or condition that affects coordination and daily functioning.
4. Speech-Language Therapy
Speech-language therapy helps people who experience difficulties with communication, speech, language, or swallowing. It may be recommended after a stroke, neurological condition, developmental delay, or other health-related event.
Some health plans include speech-language therapy within their rehabilitation or habilitation benefits.
5. Home-Based Rehabilitation
Depending on the patient's circumstances and the plan's rules, therapy may sometimes be provided at home. This can be useful for individuals who have difficulty traveling to a clinic or require rehabilitation as part of a broader home-based care plan.
However, home-based therapy can have separate eligibility and provider requirements. Do not assume that outpatient benefits automatically apply to treatment delivered at home.
What Factors Affect Physical Therapy Coverage?
Even when physical therapy is included in a plan, several factors can influence whether a specific appointment or treatment is covered.
Medical Necessity
Many health plans require treatment to be medically necessary. This generally means the service must be appropriate for evaluating, treating, or improving a documented health condition.
For example, physical therapy recommended after a knee replacement may be considered medically necessary when it forms part of an appropriate recovery plan. By contrast, general fitness training or exercise sessions undertaken solely for personal wellness may not qualify as covered therapy.
Your healthcare provider may need to document your condition, functional limitations, treatment goals, and expected progress.
Referral Requirements
Some plans require a referral from a primary care provider or another qualified healthcare professional before you can visit a physical therapist. Other plans may allow direct access to certain therapy providers, subject to state law and plan rules.
Always check whether a referral is necessary. Booking an appointment without meeting the requirement could result in unexpected costs.
Prior Authorization
Prior authorization means obtaining approval from the plan before receiving certain services. Some health plans require prior authorization for physical therapy, particularly when treatment involves an extended course of care or specialized rehabilitation.
The approval process may require information about your diagnosis, recommended treatment, number of sessions, and expected outcomes. Ask whether authorization is needed before your first appointment and whether additional approval is required if treatment continues.
Provider Network
Your plan may have a network of approved physical therapists, clinics, hospitals, and rehabilitation facilities.
Receiving treatment from an in-network provider may cost less than using an out-of-network provider. Some plans may offer limited or no coverage outside their network, except in specific circumstances. Confirm that both the therapist and the treatment location are included in your plan's network.
How Much Does Physical Therapy Cost With a Health Plan?
The amount you pay for physical therapy depends on your plan's cost-sharing arrangements and the type of service you receive. There are several common costs to understand.
Deductible: This is the amount you may need to pay for covered services before your plan begins sharing certain costs. Some services may be subject to the deductible, while others may have different arrangements.
Copayment: A copayment is a fixed amount you pay for a covered appointment or service. For example, your plan may require a set payment for each physical therapy visit.
Coinsurance: Coinsurance is the percentage of an allowed cost that you are responsible for paying after applicable deductible requirements have been met.
Out-of-pocket maximum: This is the annual limit on what you pay toward covered, eligible in-network services under applicable plan rules. Once you reach this limit, the plan generally pays the full amount for covered benefits for the remainder of the plan year. Premiums, non-covered services, and certain other expenses do not count toward this limit.
Consider a simple example.
Suppose your plan requires a copayment for each covered physical therapy appointment. If you attend several sessions every month, those individual payments can add up over time.
Another plan may apply coinsurance after you meet your deductible. In that situation, your share of the cost will depend on the allowed amount for each covered service. This is why looking only at a monthly premium is not enough. Understanding how treatment costs are shared can be just as important.
When comparing major medical plan options, review the benefits, deductibles, cost-sharing arrangements, and provider networks together.
Does Medicare Cover Physical Therapy?
Medicare also provides coverage for certain physical therapy and rehabilitation services, subject to eligibility and program requirements.
Medicare Part B helps pay for medically necessary outpatient physical therapy when the required conditions are met. A qualified healthcare provider must certify that the therapy is needed. After meeting the applicable Part B deductible, beneficiaries generally pay 20% of the Medicare-approved amount for covered outpatient physical therapy services.
Medicare may also cover medically necessary inpatient rehabilitation under Part A when a person meets the relevant requirements for inpatient rehabilitation care. The rules for outpatient therapy and inpatient rehabilitation are different, so it is important to understand which type of care you need.
For the latest details, visit the official Medicare physical therapy coverage page.
What Should You Check Before Starting Physical Therapy?
Before scheduling your first appointment, take a few minutes to confirm the details of your benefits.
Start by reviewing your Summary of Benefits and Coverage and the full plan documents. Look for sections covering rehabilitative services, habilitative services, outpatient care, and therapy benefits.
Next, confirm whether your treatment requires a referral or prior authorization. If approval is needed, find out who is responsible for submitting the request and whether it must be completed before treatment begins.
Check the provider network. Make sure the physical therapist and facility are covered under your plan, and ask whether the provider is accepting new patients.
You should also ask about visit limits. Some plans may set limits on the number of covered sessions or apply additional review requirements after a certain number of visits. Find out whether continued treatment can be approved when your healthcare provider documents an ongoing need.
Finally, request an estimate of your expected costs. Ask whether the deductible applies, whether you have a copayment or coinsurance, and whether any services may be billed separately.
Getting these answers in advance can make it easier to plan your treatment without unnecessary financial surprises.
What Happens If Your Health Plan Does Not Cover the Recommended Therapy?
If your plan does not cover a recommended treatment, do not immediately assume that you have no options.
First, ask the plan administrator for the specific reason the service was denied or excluded. There may be a missing referral, incomplete documentation, an authorization issue, or a provider-network problem.
If the decision was based on medical necessity, ask your healthcare provider whether additional clinical information can support the treatment request. You may also have the right to appeal a coverage decision. The applicable process and deadlines depend on your type of plan and the reason for the denial.
If the treatment is not covered, ask the provider about self-pay pricing, payment arrangements, or alternative treatment settings. Your healthcare provider may also be able to discuss clinically appropriate alternatives.
The important thing is to understand why coverage was denied before making a decision about stopping or changing treatment.
Choosing a Health Plan With Rehabilitation Benefits in Mind
Physical therapy may not be something you think about when comparing health plans, especially if you are currently healthy and active. However, an unexpected injury, surgery, or health condition can make rehabilitation an important part of your care.
When evaluating different options, look beyond the basic benefit summary. Consider how outpatient therapy is covered, whether inpatient rehabilitation is included, how many visits may be available, and whether referrals or prior authorization are required.
Also pay attention to the provider network and your potential out-of-pocket costs. A plan with a lower monthly premium may not necessarily be the most suitable choice if you expect to need regular specialist or rehabilitation services.
If you are reviewing coverage options for yourself or your family, you can also explore health plan information at Blue Coast Health and compare the details that matter to your healthcare needs.
Final Thoughts
Physical therapy and rehabilitation can play an important role in helping people recover from injuries, manage physical limitations, and regain independence in everyday life. Many health plans include benefits for rehabilitative and habilitative services, but the actual coverage depends on the plan, the treatment being recommended, provider requirements, and applicable rules.
Before starting treatment, take the time to understand your benefits. Check medical necessity requirements, referrals, prior authorization, network restrictions, visit limits, and expected costs.
Most importantly, do not wait until you need rehabilitation to start understanding what your health plan offers.
At Get Medical Plan, our goal is to help individuals and families better understand their health coverage options and make informed decisions. If you are exploring coverage, visit Get Medical Plan to take the next step toward understanding your options.
Disclaimer: This article is intended for general educational purposes and is not medical, legal, or benefits advice. Coverage varies by plan, state, eligibility, and individual circumstances. Always review your plan documents and confirm benefits directly with your plan administrator before receiving treatment.